The coinsurance meaning refers to the percentage of covered healthcare costs you pay after meeting your deductible, while your insurance provider covers the remaining percentage according to your policy. For example, with 20% coinsurance, you pay 20% of an eligible medical bill, and your insurer pays the other 80%. However, the exact amount you owe depends on your insurance plan, covered services, and whether you’ve met your deductible. Terms such as copay, deductible, out-of-pocket maximum, cost sharing, and insurance premium are related but have different meanings.
Coinsurance is a type of cost-sharing arrangement in health insurance that requires you to pay a percentage of your covered medical expenses while your insurance company pays the remaining amount. If you’ve come across the term “coinsurance” and wondered what it means, how it works, or how much you might have to pay for medical care, the term is closely connected to health insurance, deductibles, copayments, out-of-pocket costs, medical bills, and insurance coverage.
In this guide, you’ll learn what “coinsurance” means, how it works in health insurance, how to calculate your coinsurance costs, and how coinsurance differs from related terms such as “copay” and “deductible.” You’ll also see clear examples to make the concept easy to understand.
By the end, you’ll know exactly what coinsurance means, how it affects your medical bills, and how to use this important insurance term correctly.
1. What Is Coinsurance? Meaning and Definition
Coinsurance is the percentage of a covered healthcare service’s cost that you pay after meeting your health insurance deductible. Your insurance company pays the remaining percentage, provided the service qualifies for coverage and you follow your plan’s rules.
For example, if your plan has 20% coinsurance, you generally pay 20% of the allowed cost of a covered service, while your insurer pays the remaining 80%.
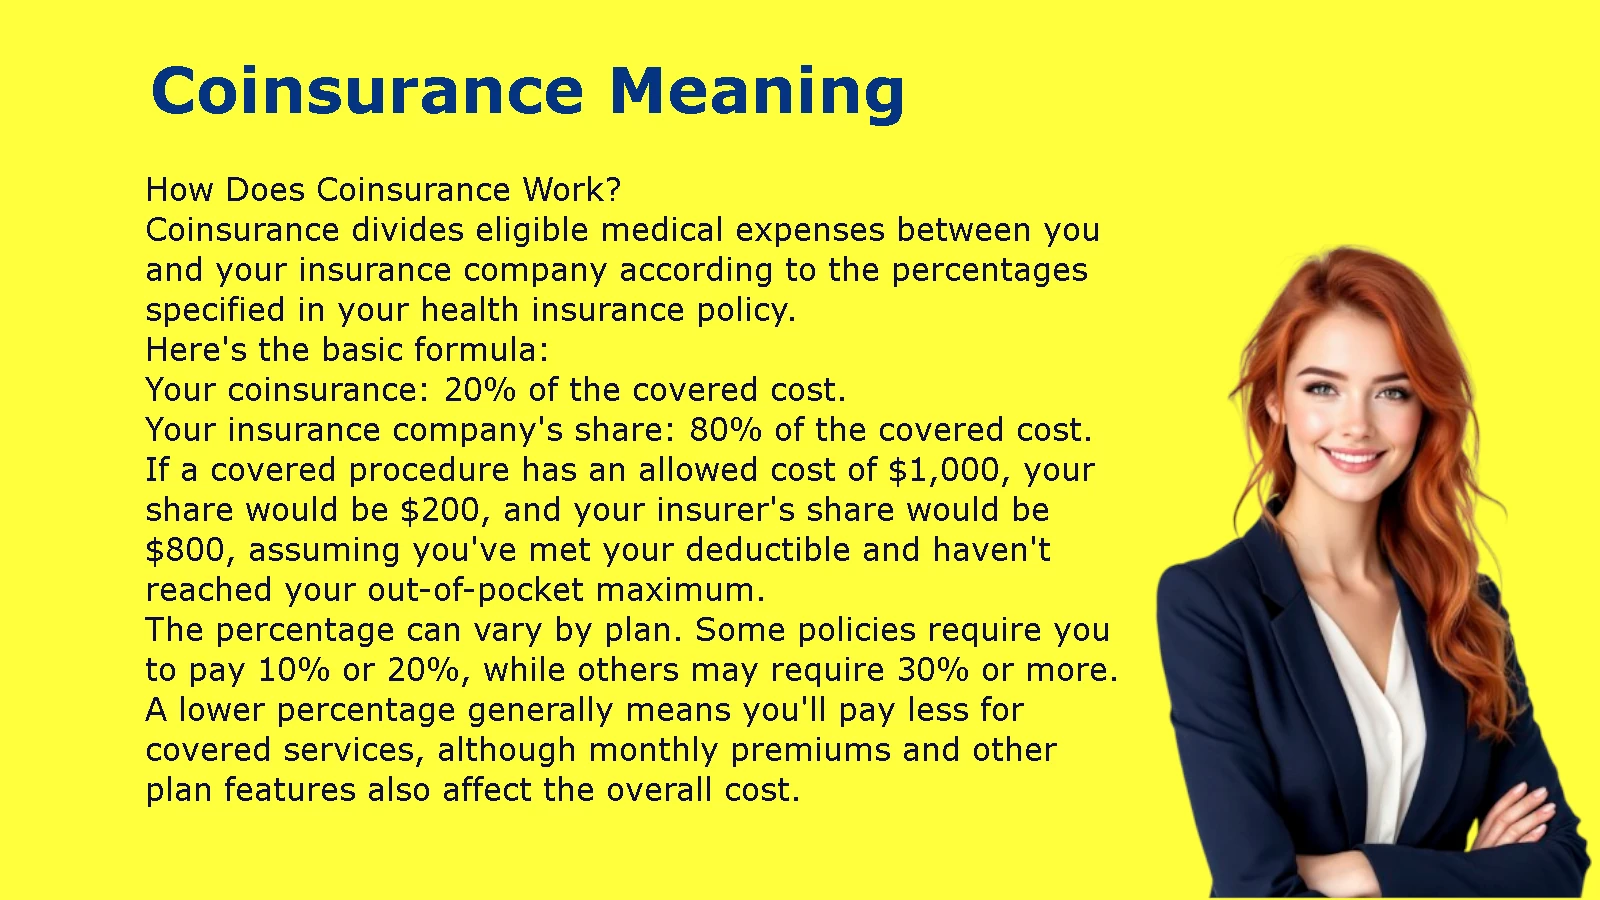
How Does Coinsurance Work?
Coinsurance divides eligible medical expenses between you and your insurance company according to the percentages specified in your health insurance policy.
Here’s the basic formula:
- Your coinsurance: 20% of the covered cost.
- Your insurance company’s share: 80% of the covered cost.
If a covered procedure has an allowed cost of $1,000, your share would be $200, and your insurer’s share would be $800, assuming you’ve met your deductible and haven’t reached your out-of-pocket maximum.
The percentage can vary by plan. Some policies require you to pay 10% or 20%, while others may require 30% or more. A lower percentage generally means you’ll pay less for covered services, although monthly premiums and other plan features also affect the overall cost.
When Does Coinsurance Start?
Coinsurance generally begins after you meet your annual health insurance deductible. Before that point, you usually pay the full allowed cost of services subject to the deductible.
For example, suppose your deductible is $1,500. You may need to pay the first $1,500 in eligible healthcare expenses yourself. Once you’ve met that amount, your plan’s coinsurance rate typically applies to additional covered services.
However, some plans cover certain preventive services or other benefits before you meet your deductible. Copays and prescription benefits may also follow different rules. Always check your policy’s benefit details to understand which services are subject to the deductible.
2. How Coinsurance Works: A Step-by-Step Example
Coinsurance determines how you and your insurer split eligible medical expenses after you satisfy your deductible. The amount you owe depends on the service’s allowed cost, your coinsurance percentage, and how much of your deductible you’ve already paid.
Consider a hospital procedure with an allowed cost of $1,000 and a health insurance plan that requires 20% coinsurance.
Step 1: Check Whether You’ve Met Your Deductible
Suppose your annual deductible is $1,500. Your coinsurance rate is 20%, and your insurer covers the remaining 80% after you meet the deductible.
Two situations can affect your bill.
Scenario A: You’ve already met your deductible.
You’ve paid $1,500 in eligible healthcare expenses earlier in the year. Your deductible is now satisfied, so coinsurance applies to the procedure’s $1,000 allowed cost.
Your share is 20% of $1,000, or $200. Your insurer pays the remaining $800, subject to the plan’s coverage rules.
Scenario B: You haven’t met your deductible.
Suppose you haven’t paid anything toward your $1,500 deductible. You generally pay the first $1,000 of the procedure’s allowed cost yourself. That amount counts toward your deductible, leaving $500 before you meet it.
You typically won’t receive the benefit of the 20% coinsurance rate for this procedure because you haven’t met your deductible yet.
If you have already paid $1,000 toward the deductible, you generally pay the remaining $500 of the procedure’s cost to satisfy the deductible. The remaining $500 of the allowed charge may then be subject to 20% coinsurance, depending on how the plan applies its deductible and benefit rules.
Step 2: Split the Medical Bill
Once you’ve met your deductible, calculating coinsurance is straightforward.
| Medical bill details | Amount |
| Allowed cost of procedure | $1,000 |
| Your coinsurance rate | 20% |
| Your share (20%) | $200 |
| Insurance company’s share (80%) | $800 |
| Total | $1,000 |
You can calculate your share using this formula:
Your payment = Allowed medical cost × Coinsurance percentage
In this example:
$1,000 × 0.20 = $200
Your insurance company generally pays the other $800.
Keep in mind that insurers often calculate cost-sharing using the plan’s allowed amount, not necessarily the provider’s original billed charge. If a hospital bills $1,500 but your insurer’s allowed amount is $1,000, your coinsurance may be based on $1,000 when you use an in-network provider.
That distinction matters because your final bill may differ from a simple percentage of the amount printed on the hospital’s invoice.
3. Coinsurance vs. Copay vs. Deductible
Coinsurance, copays, and deductibles all determine how much you pay for healthcare, but each works differently. A deductible is the amount you pay toward eligible expenses before most deductible-subject benefits begin, a copay is a fixed fee for a service, and coinsurance is your percentage of an allowed cost.
| Term | What It Means | When You Pay It | Payment Type |
| Deductible | The amount you pay toward eligible healthcare costs before most applicable insurance benefits begin | As you receive services during the plan year, until you meet the deductible | Fixed annual threshold |
| Copay | A fixed fee for a covered service, such as a doctor’s visit or prescription | At the time of service or when the bill is due, depending on the plan | Fixed dollar amount |
| Coinsurance | Your percentage share of a covered service’s allowed cost | Usually after meeting the applicable deductible | Percentage of cost |
What Is the Difference Between Coinsurance and a Deductible?
Your deductible determines how much you must pay toward eligible healthcare expenses before your plan begins sharing costs for services subject to the deductible. Coinsurance determines your share of eligible costs after that requirement has been satisfied.
For instance, imagine you have a $1,500 deductible and 20% coinsurance. You generally pay the first $1,500 in applicable costs yourself. After meeting that deductible, you typically pay 20% of additional covered expenses, while your insurer pays 80%.
The deductible and coinsurance work together, so you should consider both when comparing health insurance plans.
What Is the Difference Between Coinsurance and a Copay?
A copay is a fixed amount, while coinsurance is a percentage. A plan might charge you a $30 copay for a primary care visit but require 20% coinsurance for an outpatient procedure.
For example, a $200 allowed office visit with a $30 copay generally costs you $30 for that visit. With 20% coinsurance, the same $200 allowed cost would result in a $40 payment.
Your plan may apply copays before the deductible for certain services, while other benefits may require you to meet the deductible first. Check your policy to determine which rule applies.
Which Costs Less: A Copay or Coinsurance?
Neither option always costs less. Your actual payment depends on the service’s allowed cost and the terms of your policy.
Consider these examples:
- Copay: You pay $30 for a covered office visit, regardless of whether the allowed cost is $150 or $200, assuming the same copay applies.
- Coinsurance: You pay $30 on a $150 allowed charge at 20%, or $40 on a $200 allowed charge at 20%.
A copay can make routine expenses more predictable. Coinsurance may be relatively inexpensive for low-cost services but become expensive when you need surgery, hospital care, or other costly treatment.
Before choosing a plan, compare its premiums, deductible, copays, coinsurance rates, and out-of-pocket maximum rather than focusing on a single feature.
4. The Safety Net: Out-of-Pocket Maximum
An out-of-pocket maximum is the most you must pay during a plan year for covered, in-network essential health benefits under an applicable health insurance plan, subject to the plan’s rules. Once you reach this limit, your insurer generally pays 100% of covered, in-network costs for the rest of that plan year.
This limit helps protect you from unlimited cost-sharing when you face expensive medical treatment. It usually includes qualifying payments toward your deductible, copays, and coinsurance. Monthly premiums, noncovered services, and certain out-of-network expenses generally don’t count toward the limit.
How Does the Out-of-Pocket Maximum Work?
Imagine your health insurance plan has these features:
- Annual deductible: $2,000
- Coinsurance: 20%
- Out-of-pocket maximum: $6,000
You have surgery and need follow-up treatment throughout the year. You pay your deductible first, followed by coinsurance on applicable covered services.
As you pay eligible deductibles, copays, and coinsurance, your spending accumulates toward the $6,000 out-of-pocket maximum.
Suppose you’ve already paid $5,800 in qualifying expenses. Your next covered, in-network service would normally require $500 in coinsurance. However, you only have $200 left before reaching your maximum.
You generally pay that remaining $200. After reaching $6,000, your plan pays 100% of covered, in-network services for the remainder of the plan year.
| Cost-sharing detail | Amount |
| Out-of-pocket maximum | $6,000 |
| Qualifying expenses already paid | $5,800 |
| Remaining amount before reaching the limit | $200 |
| Additional qualifying payment required | $200 |
| Payment for subsequent covered, in-network services | $0 |
These figures assume all listed expenses qualify toward the limit and the services fall under the plan’s coverage rules.
When Does Coinsurance Stop?
Coinsurance generally stops when you reach your plan’s applicable out-of-pocket maximum for covered, in-network services. From that point until the plan year ends, your insurer pays 100% of those covered costs.
However, reaching your limit doesn’t make every healthcare service free. You may still owe money for:
- Monthly insurance premiums.
- Services your plan doesn’t cover.
- Certain out-of-network care.
- Charges that don’t qualify toward your out-of-pocket maximum.
- Care received outside your plan’s applicable benefit rules.
For this reason, review both the deductible and out-of-pocket maximum when selecting coverage. A plan with a low monthly premium may still expose you to substantial costs if you need frequent or expensive treatment.
5. Summary: Key Takeaways About Coinsurance
Coinsurance determines your percentage of eligible healthcare costs after you meet the applicable deductible. Understanding your rate, network rules, and out-of-pocket maximum can help you estimate medical expenses and choose a plan that fits your budget.
Higher Coinsurance Can Mean Higher Financial Risk
Plans with lower monthly premiums sometimes require higher coinsurance, such as 30% or 40%. These plans may appeal to people who want to reduce their regular premium payments, but they can become expensive when significant medical treatment is necessary.
Consider two hypothetical plans covering the same $10,000 allowed medical expense after you’ve met the deductible.
| Feature | Plan A | Plan B |
| Monthly premium | $350 | $250 |
| Annual premiums | $4,200 | $3,000 |
| Coinsurance | 20% | 40% |
| Your share of a $10,000 allowed expense | $2,000 | $4,000 |
| Annual premium plus this medical expense | $6,200 | $7,000 |
In this example, Plan B saves you $1,200 in annual premiums but costs an additional $2,000 for the medical procedure. Your combined cost is therefore $800 higher than with Plan A.
These figures are illustrative and exclude deductibles, copays, and other potential expenses. Actual costs also depend on each plan’s out-of-pocket maximum and coverage terms.
The lesson: Don’t choose health insurance based on its monthly premium alone. Estimate your total annual costs under different healthcare scenarios, including a year with substantial medical expenses.
In-Network vs. Out-of-Network Coinsurance
Your coinsurance rate can change significantly depending on whether you receive care from an in-network or out-of-network provider.
In-network providers have agreements with your insurance company to accept negotiated rates for covered services. Your plan generally offers lower cost-sharing when you use these providers.
Out-of-network providers don’t have the same contractual relationship with your insurer. Depending on your plan, you may face higher coinsurance, separate deductibles, balance billing, or no coverage for nonemergency care.
For example, your plan might require 20% coinsurance for an in-network procedure but 40% for an out-of-network procedure. Some plans, such as certain HMOs, generally don’t cover routine out-of-network care except in specified circumstances.
Even when your insurer covers out-of-network care, the provider may charge more than the insurer’s allowed amount. You could owe the difference in addition to your normal cost-sharing, unless applicable law or plan terms protect you from those charges.
Before scheduling a procedure, take these steps:
- Confirm network status. Check whether the hospital, specialist, and other relevant providers participate in your plan.
- Request a cost estimate. Ask your insurer for the allowed amount, deductible status, coinsurance rate, and estimated patient responsibility.
- Check your remaining out-of-pocket maximum. This helps you estimate how much more you may need to pay for qualifying services during the year.
- Review the coverage rules. Ask whether the procedure requires prior authorization or a referral.
These checks can help you avoid unexpected bills and make a more informed healthcare decision.
Final Thoughts: Understand Your Coinsurance Before You Need Care
Coinsurance determines how you share the cost of covered healthcare with your insurer. Once you meet the applicable deductible, your plan’s percentage determines your share of eligible medical expenses. Your out-of-pocket maximum then limits qualifying cost-sharing for covered services under the plan’s rules.
Before choosing a policy, compare the deductible, coinsurance rate, monthly premium, provider network, and out-of-pocket maximum. Don’t overlook the difference between in-network and out-of-network care, either.
Your next step: Review your insurance policy or Summary of Benefits and Coverage. Find the coinsurance percentage for primary care, specialist visits, hospital stays, and outpatient procedures. Then compare those figures with the plan’s deductible and out-of-pocket maximum.
A few minutes of preparation can help you choose coverage with greater confidence and reduce the risk of an unpleasant financial surprise when you need medical care.